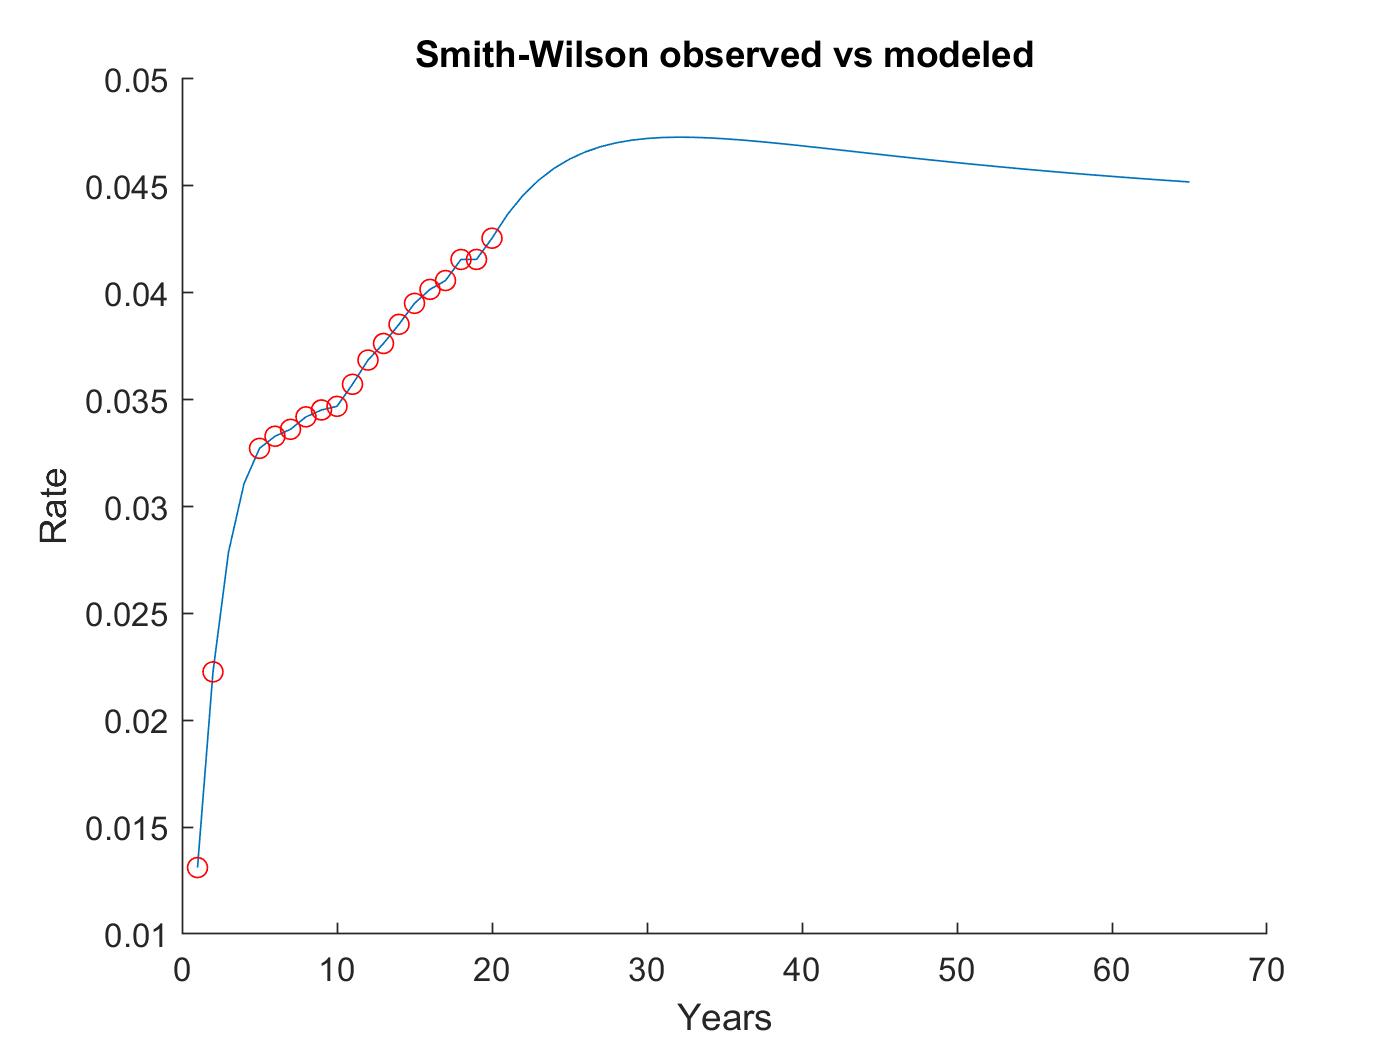
Smith & Wilson algorithm
Smith & Wilson is a popular algorithm for approximating financial curves such as bond yields or rates.

引用格式
Gregor Fabjan (2026). Smith & Wilson algorithm (https://github.com/open-source-modelling/smith_wilson_matlab), GitHub. 检索时间: .

| 版本 | 已发布 | 发行说明 | Action |
|---|---|---|---|
| 1.1.7 | Link to repository updated |
||
| 1.1.3 | Updated to a working GitHub link |
||
| 1.1.2 | Forgot to include T_Obs = [1; 2; 4; 5; 6; 7] in the example |
||
| 1.1.1 | Minor fixes |
||
| 1.1.0 | Typo in SWExtrapolate |
||
| 1.0.9 | Minor formating changes |
||
| 1.0.8 | Added link to GitHub |
||
| 1.0.7 | Reformated the documentation for better clarity. |
||
| 1.0.6 | Fixed name of SWExtrapolate function in description |
||
| 1.0.5 | Fixed the name of SWCalibrate in the description |
||
| 1.0.4 | Per request added an example of use in the description |
||
| 1.0.3 | Added a link to the Excel example. |
||
| 1.0.2 | Removed repetitive parts of the description |
||
| 1.0.1 | Conversion of the file main.mlx to main.m. |
||
| 1.0.0 |

